
Copperlane
Copperlane · Business
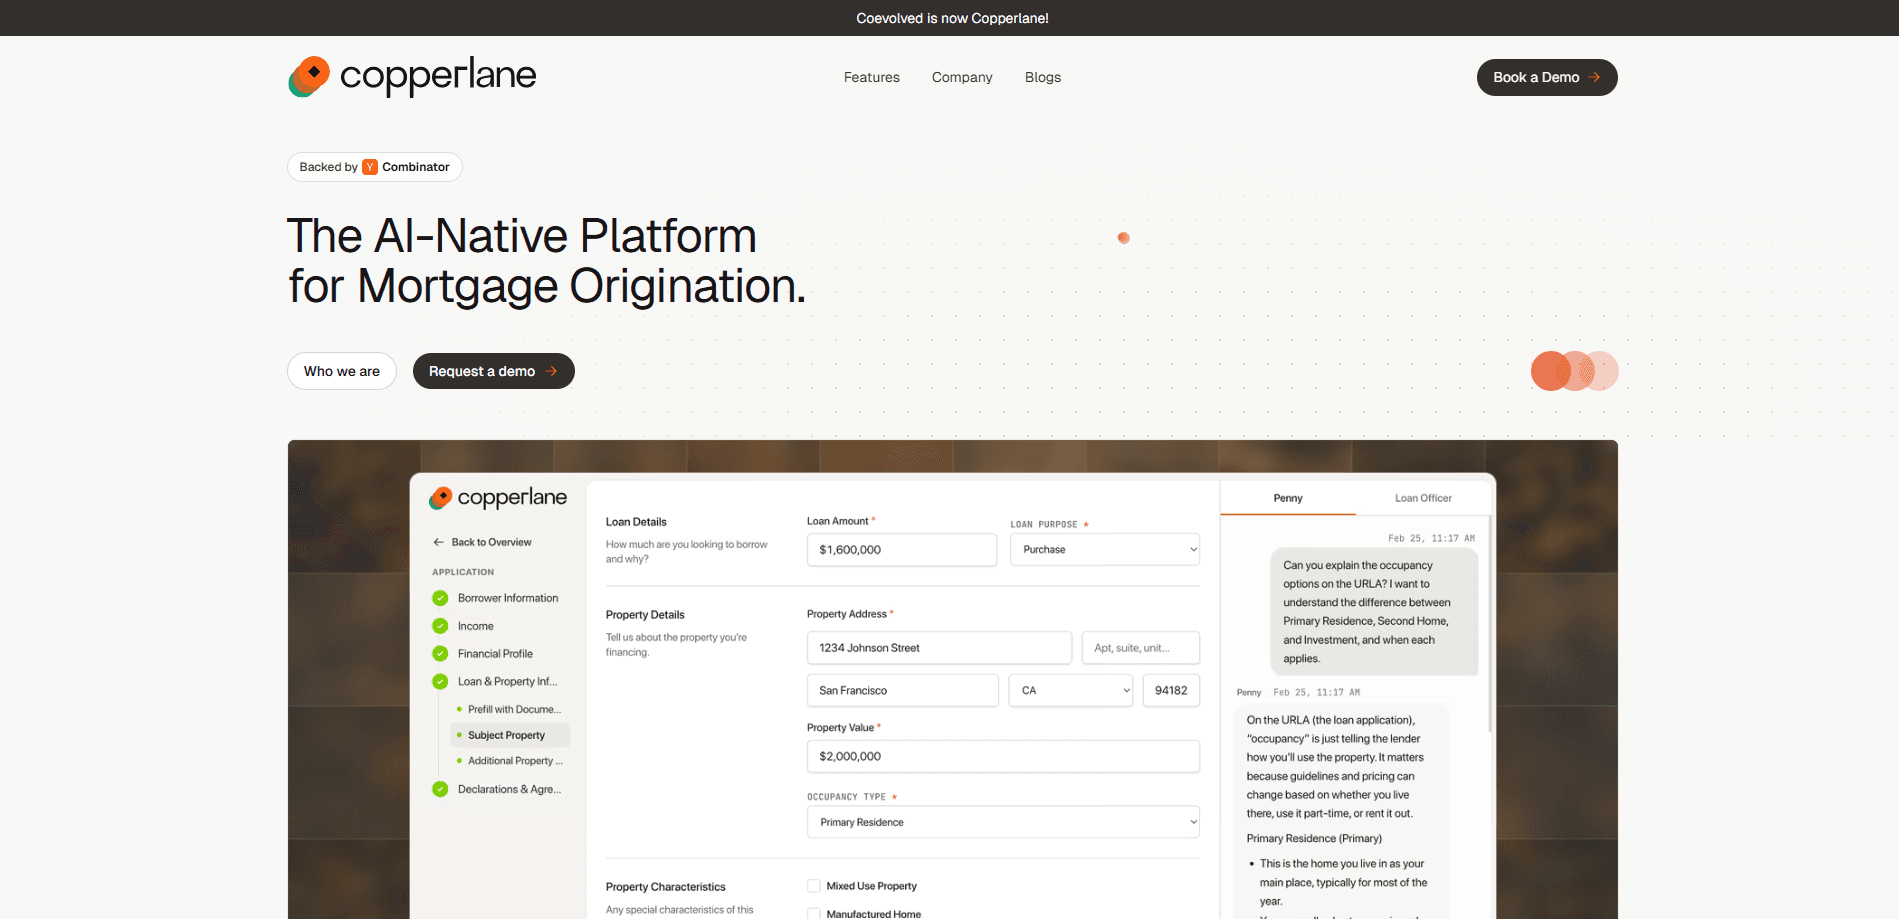
Copperlane is an AI mortgage origination platform built for lenders, loan officers, and the borrowers they serve. Its core product is Penny, an AI mortgage loan officer assistant that reads application documents, spots missing or unusual items, and asks borrowers the right questions before a file ever reaches underwriting. The platform sits between the borrower and the loan officer, turning scattered emails and repeated follow-ups into a structured, traceable case file.
About Copperlane
What Is Copperlane
Copperlane is a software company trying to remove the manual grind from mortgage lending. It's a coordination problem. Most of a mortgage file gets stuck in waiting, not in the math: someone waits on a bank statement, a loan officer chases a signature, and a borrower has no idea where things stand. Copperlane's answer is Penny, a mortgage loan officer assistant that handles that back and forth automatically.
The platform pairs an AI-native document workflow with a human-in-the-loop design. Penny collects files, verifies complex documents, and flags issues an underwriter would normally catch, then hands a distilled recommendation to a real loan officer who makes the final call. According to Copperlane, that review step can shrink a four-hour manual process into minutes.
The biggest limitation is who it's for. Copperlane sells to lenders and mortgage teams, not to individual homebuyers browsing for a loan. No self-serve signup. No public price list. No consumer app. A regular borrower can't just download it and apply.
Getting Started
- Book a demo with the Copperlane team and describe how your lending pipeline currently handles intake and document review.
- Connect Penny to your existing borrower portal and system of record so it can read and coordinate data across the systems your loans already touch.
- Configure the questions and document rules Penny should use for your loan products, including what triggers a clarification request.
- Let Penny collect documents from borrowers over text, voice, and email, then review the distilled recommendations she produces.
- Have loan officers approve the final recommendation and keep every decision on the record.
Product Information
A quick look at Copperlane's pricing, supported platforms, and performance.
Best for
The users, tasks, and scenarios where this tool fits best.
Users
- Mortgage lenders
- Loan officers
- First-time homebuyers
Tasks
- Automated document verification
- Drafting explanations
- Pre-approval analysis
Scenarios
- Handling a spike in application volume without adding headcount
- Answering borrower questions outside business hours
- Cleaning up a messy file before it hits underwriting
Key features
Penny, the AI loan officer assistant
Penny is the whole point of the product. She reads application documents, asks borrowers targeted questions, and produces recommendations a loan officer can act on. Copperlane pitches her as a generalized reasoner rather than a rigid rule engine. That matters. Real mortgage files rarely fit a clean template.
Intelligent document verification
Copperlane automates the review of complex documents, including the pre-approval analysis that normally lands on a person's desk. The company says this compresses a process that can take a loan officer up to four hours into minutes. Big difference. For a lender, that's the gap between reviewing a handful of files a day and a much larger stack.
Universal integration
Penny plugs into a lender's existing borrower portal and system of record, coordinating data across the systems a loan touches instead of forcing a rip-and-replace. That's a real plus. Established lenders carry years of tooling, so adoption doesn't mean rebuilding the stack.
Proactive issue detection
At the application stage, Penny reviews bank statements and catches things an underwriter would flag, such as large deposits that don't match typical income patterns. Why does that matter? Because a missing explanation is exactly what stalls a file later. She then asks the borrower for clarification and can generate a compliant letter of explanation before the file reaches underwriting. Catching those issues early is what stops the late-stage surprises.
Multi-channel borrower support
Copperlane reaches borrowers over text, voice, and email, around the clock, and follows up proactively rather than waiting for a reply. For people juggling jobs or unfamiliar systems, that removes a lot of the anxiety of not knowing what's next. Silence is the enemy here.
Human-in-the-loop decisions
Penny never signs off on a loan. She automates the internal back and forth and advises the loan officer, who stays in control of the final recommendation. That's loan origination automation with a brake built in. It keeps a person accountable for every decision, which matters in a regulated, high-stakes industry.
Pros and cons
Pros
- Cuts the manual document review that can take hours down to minutes, according to Copperlane.
- Works with a lender's existing portal and system of record instead of demanding a full replacement.
- Reaches borrowers over text, voice, and email at any hour, with proactive follow-ups.
- Keeps a human loan officer in charge of every final decision.
- Targets a genuine pain point, since mortgage origination stays slow and expensive even in the digital era.
Cons
- It's a business product, so individual homebuyers can't use it directly.
- Pricing isn't published, which means you have to talk to sales before you know the cost.
- The platform is new, having launched in mid-2026, so there's little independent track record to check.
- Results depend on integrating with your existing system of record, which not every lender can do cleanly.
Frequently asked questions
Copperlane runs the document and coordination side of mortgage origination using its AI agent, Penny. She collects borrower documents, verifies them, flags issues, and hands a distilled recommendation to a loan officer.
Related content
Explore related tools, skills, and articles for Copperlane.
Copperlane Alternatives

Claude for Google Workspace
Anthropic · Writing · Productivity · BusinessClaude for Google Workspace puts Claude in a sidebar inside Google Docs, Sheets, and Slides, where it reads the file you have open and edits it in place.

KloudMate 2.0
KloudMate · Coding · BusinessKloudMate 2.0 is an AI observability platform that keeps logs, metrics, traces, and incidents in one place, with KloudMate Assistant investigating alerts and proposing the fix.
Cekura Bench
Cekura · Voice & Language · BusinessCekura Bench is a public benchmark that runs speech-to-speech models and deployed voice agents through 82 simulated phone calls, three times each, then publishes pass rates, latency and cost.